The political appeal of “mandatory prison for fraud” is obvious; the policy mechanics are not. President Trump’s call to hard-wire custody for Medicare, Medicaid, and Social Security fraud sits at the intersection of public anger at theft from social insurance and the quiet reality that federal fraud sentencing already hinges on loss amounts, guidelines, and prosecutorial leverage more than on statutory minimums. Understanding that tension is the key to judging what this proposal could actually change—and what it cannot.
At a Glance
- Trump urged Congress to impose mandatory prison terms for fraud against Medicare, Medicaid, and Social Security, with escalating penalties by loss and doubled terms for repeat offenders.
- He framed the push as deterrence to protect programs serving seniors, children, and the sick; he also floated personal liability for politicians who knowingly ignore preventable fraud.
- Under current law, health care fraud already carries substantial prison exposure, but true mandatory-minimum applicability in benefits-fraud cases is relatively rare.
- Critics argue mandatory minimums can be blunt, create arbitrary outcomes, and displace judicial discretion without clear gains in deterrence.
What was proposed and why it resonates
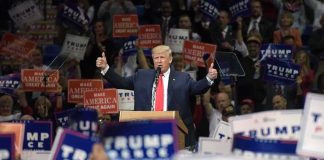
In a White House video address, President Trump called on Congress to create mandatory prison sentences for those who defraud Medicare, Medicaid, and Social Security, to bar probation in such cases, to scale punishment with the amount stolen, and to double sentences for repeat offenders. He tied the package to deterrence and to safeguarding programs designed to “take care of the sick, feed the hungry, care for our children, and protect our senior citizens’ retirements.” The rhetoric tracks a familiar pattern: large, vivid fraud examples make a powerful case for certainty and severity of punishment, and elected officials respond with proposals that promise both. The recorded statement is clear on the direction of travel—custody-first sentencing with enhancements for loss and recidivism—even if it stops short of specifying statutory thresholds or text.
The emphasis on certainty has intuitive appeal. Audiences can readily call to mind headline cases—from multimillion-dollar Medicaid schemes to sprawling billing conspiracies—and the notion that guaranteed prison time will deter the next would-be fraudster feels proportionate to the harm. The political logic is equally straightforward: tough-on-fraud posture signals protection of taxpayers and beneficiaries, especially seniors, who are seen as collateral victims of program theft.
How current law already works—and where mandatory minimums actually bite
Federal law already treats health-care fraud as a serious felony exposure. The Centers for Medicare & Medicaid Services’ own overview notes imprisonment up to 10 years for core health care fraud offenses, with higher maxima when harm or death result. That is not a mandatory minimum; it is a statutory ceiling that judges may approach or stay far below depending on the Guidelines, facts, and a defendant’s history. In practice, sentence length in fraud turns heavily on “loss” calculations under the Federal Sentencing Guidelines—how much was taken, how many victims, whether sophisticated means were used—and on charging decisions that can add or remove leverage.
The data for government benefits fraud underscores how uncommon true mandatory-minimum exposure is in this space. Recent U.S. Sentencing Commission snapshots report only a small fraction of government benefits fraud defendants are convicted of offenses carrying a mandatory minimum at all, and a nontrivial share of those are ultimately relieved of that minimum through safety valves or other mechanisms. Put differently, the day-to-day system is already dominated by judicial and prosecutorial discretion, not fixed floors that lock courts into lengthy terms.
The unresolved details that determine whether this would change outcomes
Because the proposal is a call to Congress rather than introduced bill text, critical mechanics remain unspecified. Which statutes would carry a floor, and at what dollar thresholds? Would the mandatory term attach to any fraud against Medicare, Medicaid, or Social Security, or only to losses above defined levels? How would repeat-offender “doubling” interact with the Guidelines, acceptance of responsibility, cooperation, or safety valves? Would an across-the-board no-probation rule survive the hard cases—a low-level participant whose “loss” attribution reflects enterprise totals rather than personal gain, or a provider whose billing errors were recklessly indifferent rather than intentionally deceitful? Without answers, it is difficult to gauge how many additional defendants would move from probationary or short-custody outcomes to guaranteed multi-year terms.
The most novel element—personal liability for state and local politicians who know about fraud and could stop it but do not—also lacks a clear legal vehicle. There are analogues in civil false-claims and fiduciary-duty regimes, but attaching personal damages to elected officials for inaction raises immediate questions of knowledge standards, causation, immunities, and constitutional vagueness. Any eventual text would have to define those gates tightly to avoid sweeping in policy disagreements or resource-allocation choices rather than willful facilitation of theft.
The case for and against mandatory minimums in fraud
Supporters argue certainty deters: if every fraud against safety-net programs guarantees prison, the expected cost of crime rises and marginal offenders will walk away. They also argue consistency and moral clarity—stealing from the sick and elderly is not a bookkeeping error, and consequences should reflect that. That case is emotionally forceful and politically saleable, particularly when paired with severe outlier cases and eye-watering aggregate figures in suspicious-activity reporting.
Critics answer on three fronts. First, instrumentation: mandatory minimums can be blunt. Advocacy groups and policy analysts have long warned of “cliff effects,” where crossing a numeric loss threshold triggers a large, mechanical jump in punishment irrespective of role or culpability, and “tariff effects,” where minimums pull sentences upward across an offense class. That dynamic risks over-penalizing low-level or peripheral actors when loss is attributed broadly.
Second, discretion and accuracy: defense organizations caution that fraud loss calculations can incorporate accounting disputes or overpayment determinations that inflate amounts; in systems that equate loss with punishment floors, questionable math can drive custodial outcomes that a judge would otherwise modulate. Overseas reviews of benefit-fraud sentencing have echoed those concerns in the context of administrative error and inflated overpayments.
Third, efficacy: empirical support that mandatory minimums outperform guideline-driven, judge-supervised sentencing in deterring white-collar fraud is thin. If the binding constraint on many fraudsters is detection risk rather than marginal sentence length, investments in audits, analytics, and swift case processing may buy more deterrence per dollar than hard floors. Some criminological syntheses and policy submissions have, accordingly, urged calibrated alternatives—restitution-first models, targeted incapacitation for ringleaders, and community or financial sanctions for lower-level actors—over universal custody requirements.
What would a rigorous version look like?
If Congress were to operationalize the President’s objectives while addressing the main criticisms, three design choices would matter. First, narrow triggering conduct with mens rea precision: limit mandatory floors to intentional, knowing schemes to defraud, proved beyond reasonable doubt, and exclude mere billing negligence or ambiguous documentation failures. Second, scale by individualized loss and role: tether any floor to the defendant’s reasonably foreseeable loss contribution, with carve-outs for minimal participants and cooperation incentives intact. Third, align with adjudicative accuracy: require reliable loss proof, allow for judicial findings to correct inflated administrative overpayment figures, and maintain safety valves for atypical, low-culpability scenarios. Those elements would not mollify all concerns, but they would target the prison-guarantee at the core fraudsters the proposal aims to deter rather than at the penumbral cases it risks sweeping in.
Donald Trump calls for for Congress to pass MANDATORY prison sentences for ALL Medicare, Medicaid and Social Security programs fraudsters
Under this proposal if any politicians knows about fraud taking place they too will be held accountable
“Today, I'm calling on Congress to…
— TNT (@tnt_updates) October 4, 2026
The bottom line for beneficiaries, taxpayers, and courts
The animating principle behind the President’s push is sound: social insurance depends on trust, and theft from those systems corrodes public willingness to fund and defend them. The question is implementation. Health-care and benefits fraud already expose offenders to serious prison time; mandatory minimums would convert some portion of judicial discretion into floor-setting by statute. If the lines are bright and well-calibrated, they may incapacitate the worst actors more reliably; if they are blunt or tethered to noisy loss metrics, they may produce arbitrary outcomes and new litigation without a commensurate deterrent dividend. As always in sentencing policy, the craftsmanship of the statute—and the quality of enforcement in the field—will determine whether this is reform or rhetoric.
Sources:
pulse.com.gh, newsmax.com, whitehouse.gov, cms.gov, gov.ca.gov, nacdl.org